


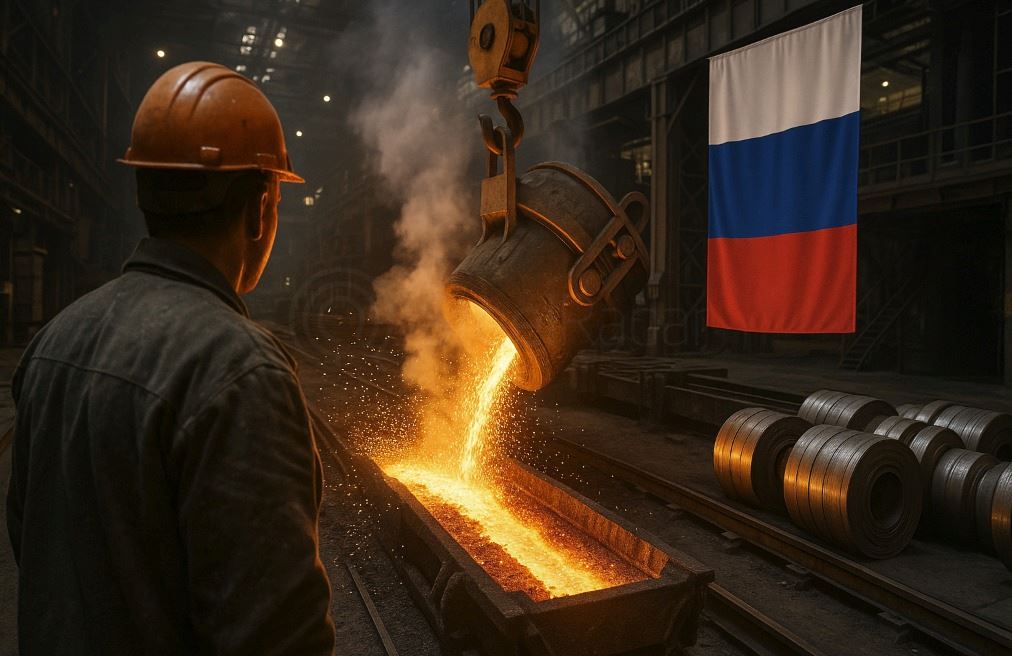
Billet export prices supported by logistics
Russian billet export indications have moved slightly higher over the past week. Billet is currently assessed at around $475/t FOB Black Sea, compared with $465–475/t FOB previously. However, the increase should not be interpreted as a sign of a strong recovery in trading activity. The market remains thin, with a significant share of FOB indications still considered nominal.
A reported deal for 15,000 tonnes of Russian-origin material at around $485/t CFR Taiwan provides some evidence that buyers in Asia are still willing to consider Russian material at current levels. Nevertheless, overall transaction activity remains limited.
The Turkish market is also showing relatively firm Russian billet offers, currently around $515–520/t CFR Zonguldak/Bartin and $520–525/t CFR Marmara. Higher freight costs, particularly from the Black Sea, are making negotiations more difficult. Freight on the Novorossiysk–Marmara route has reportedly increased by approximately $4–7/t, limiting the scope for Russian producers to reduce their offers.
As a result, suppliers are largely attempting to preserve existing price levels rather than chase additional sales through aggressive discounts.
Logistics are becoming the central issue for exports
The Russian export market is increasingly being shaped by logistics rather than production economics alone. Restrictions affecting Black Sea and Azov ports are forcing exporters to examine alternative routes, but none currently offers a straightforward replacement.
The Baltic Sea has become a more interesting option as freight rates towards Mediterranean destinations have fallen to around $60/t. However, available port and vessel capacity remains limited, with other cargoes competing heavily for shipping space. This significantly reduces the ability of steel exporters to scale up shipments even when freight economics appear relatively attractive.
Murmansk offers another potential route, with freight to the Marmara region estimated at around $50/t. Yet the port's current focus on other cargoes, particularly scrap, means that it cannot immediately provide the capacity required to become a major billet-export corridor.
The Astrakhan–Iran route has also become less competitive. Reduced vessel availability through Iranian ports has pushed freight costs higher, weakening the economics of shipments through the Caspian. For exporters already operating under tight margins, this makes the route increasingly difficult to justify.
The result is a fragmented export logistics system in which Russian mills may have material available but lack sufficient reliable shipping capacity to place it competitively in international markets.
Stronger rouble limits export flexibility
Currency movements are adding another layer of pressure. The stronger rouble has reduced the attractiveness of export sales at a time when Russian producers are already dealing with higher logistics and operating costs.
This combination is particularly important for billet exporters. Lower export prices could help stimulate demand, but producers have limited room to make concessions because transportation and domestic production costs are moving in the opposite direction.
The $470/t FOB CIS billet assessment, up by $5/t, reflects this broader shift in the cost structure. Russian producers therefore appear more focused on protecting margins than on pursuing volume through lower export prices.
Domestic steel demand has recovered from the first-half weakness
While exports remain difficult, the domestic Russian steel market has shown a stronger performance over the summer.
The sharp decline in steel production and apparent consumption during the first quarter heavily influenced first-half results. However, demand improved considerably during the summer, while steel output between June and August reached levels exceeded only by the exceptional figures recorded in 2023.
The recovery has also been accompanied by higher domestic steel prices, particularly for long products and sections. One important factor behind the price increase was extremely low inventory throughout the distribution chain. After months of weak demand, producers and distributors had reduced stocks to minimum levels, leaving the market with little buffer when consumption started to recover.
This means that the summer price increase was not simply a consequence of stronger underlying demand. Low inventories amplified the impact of the recovery, creating a temporary shortage of readily available material.
Government-supported infrastructure spending, reconstruction and projects related to protection of infrastructure have provided additional support to steel consumption. Housing construction has also shown some improvement following the weakness seen at the beginning of the year.
At the same time, manufacturing sectors outside government-supported activities remain under significant pressure. High borrowing costs continue to restrict investment and private-sector activity, while the Central Bank's key rate remains at 14%.
Long products remain more vulnerable than flat steel
The market outlook differs considerably between product segments.
Flat steel currently appears relatively better positioned. Major mills have already secured a significant portion of their October order books, particularly through direct sales to end-users. Producers are also expected to manage supply through maintenance at rolling facilities and increased exports via Baltic ports.
Long products, particularly rebar and welded pipe, face a more difficult environment. Although infrastructure projects and reconstruction-related demand continue to provide support, the underlying commercial market remains weak.
For these products, supply-side adjustment may become increasingly important. Producers could be forced to reduce output towards second-quarter levels if demand fails to maintain its summer momentum.
Chinese competition is becoming a structural problem
Russian steelmakers are also facing growing pressure from Chinese suppliers. China's export expansion is no longer limited to a temporary increase in shipments; it is becoming a structural competitive factor across multiple steel-consuming segments.
Chinese exports of wire and fastener-related steel products have increased substantially over the past decade, while China's share of overlapping product ranges in the Russian market has continued to rise. The fact that Chinese imports increased even faster into Russia than globally highlights the growing competitiveness of Chinese producers in the Russian market.
This competition is likely to remain a major challenge for Russian manufacturers, particularly as domestic demand remains constrained and producers increasingly depend on export markets to balance their sales.
Raw material costs provide some support
One of the more supportive developments for Russian steel producers is the sharp increase in metallurgical coal prices in Asian markets.
Russian coking coal prices have risen significantly since the beginning of the year, supported by tighter availability in China, strong Indian demand and supply disruptions among major exporters. Chinese buyers have increased their purchases of Russian coal, while uncertainty surrounding Mongolian supply has added further support to the market.
Higher raw material prices are positive for Russian coal exporters, but they also represent an additional cost pressure for steel producers. The sustainability of the current coal rally remains uncertain, with additional Chinese production and a potential recovery in Mongolian exports creating the possibility of a correction later in the year.
Outlook
The Russian steel market is currently being pulled in two different directions.
On the domestic side, the summer recovery has provided much-needed support after a weak first half of the year. Low inventories, government spending and stronger activity in selected construction and infrastructure segments have allowed producers to raise prices and partially recover margins.
The export picture is considerably more complicated. Black Sea and Azov logistics remain the key constraint, while alternative routes through the Baltic, Murmansk and the Caspian offer only limited capacity or less attractive economics. Higher freight costs and the stronger rouble further reduce exporters' flexibility.
As a result, Russian billet prices are likely to remain relatively firm in the near term despite limited transaction volumes. The market has little incentive for producers to make significant concessions while logistics continue to absorb a growing share of export economics.
The key question for the coming weeks will therefore be whether logistics can improve enough to convert current price indications into actual transactions. If shipping capacity remains restricted, Russian exporters may continue to prioritize margin protection and domestic sales over aggressive export volumes.
Overall, the Russian steel market is not currently facing a straightforward supply shortage. Instead, it is dealing with a disconnect between available material, effective demand and the ability to move steel efficiently between markets. This logistical imbalance, combined with tight monetary conditions and increasing Chinese competition, is likely to remain the defining feature of the Russian steel market in the coming weeks.


Comments
No comment yet.